Mastering Careers & Skills
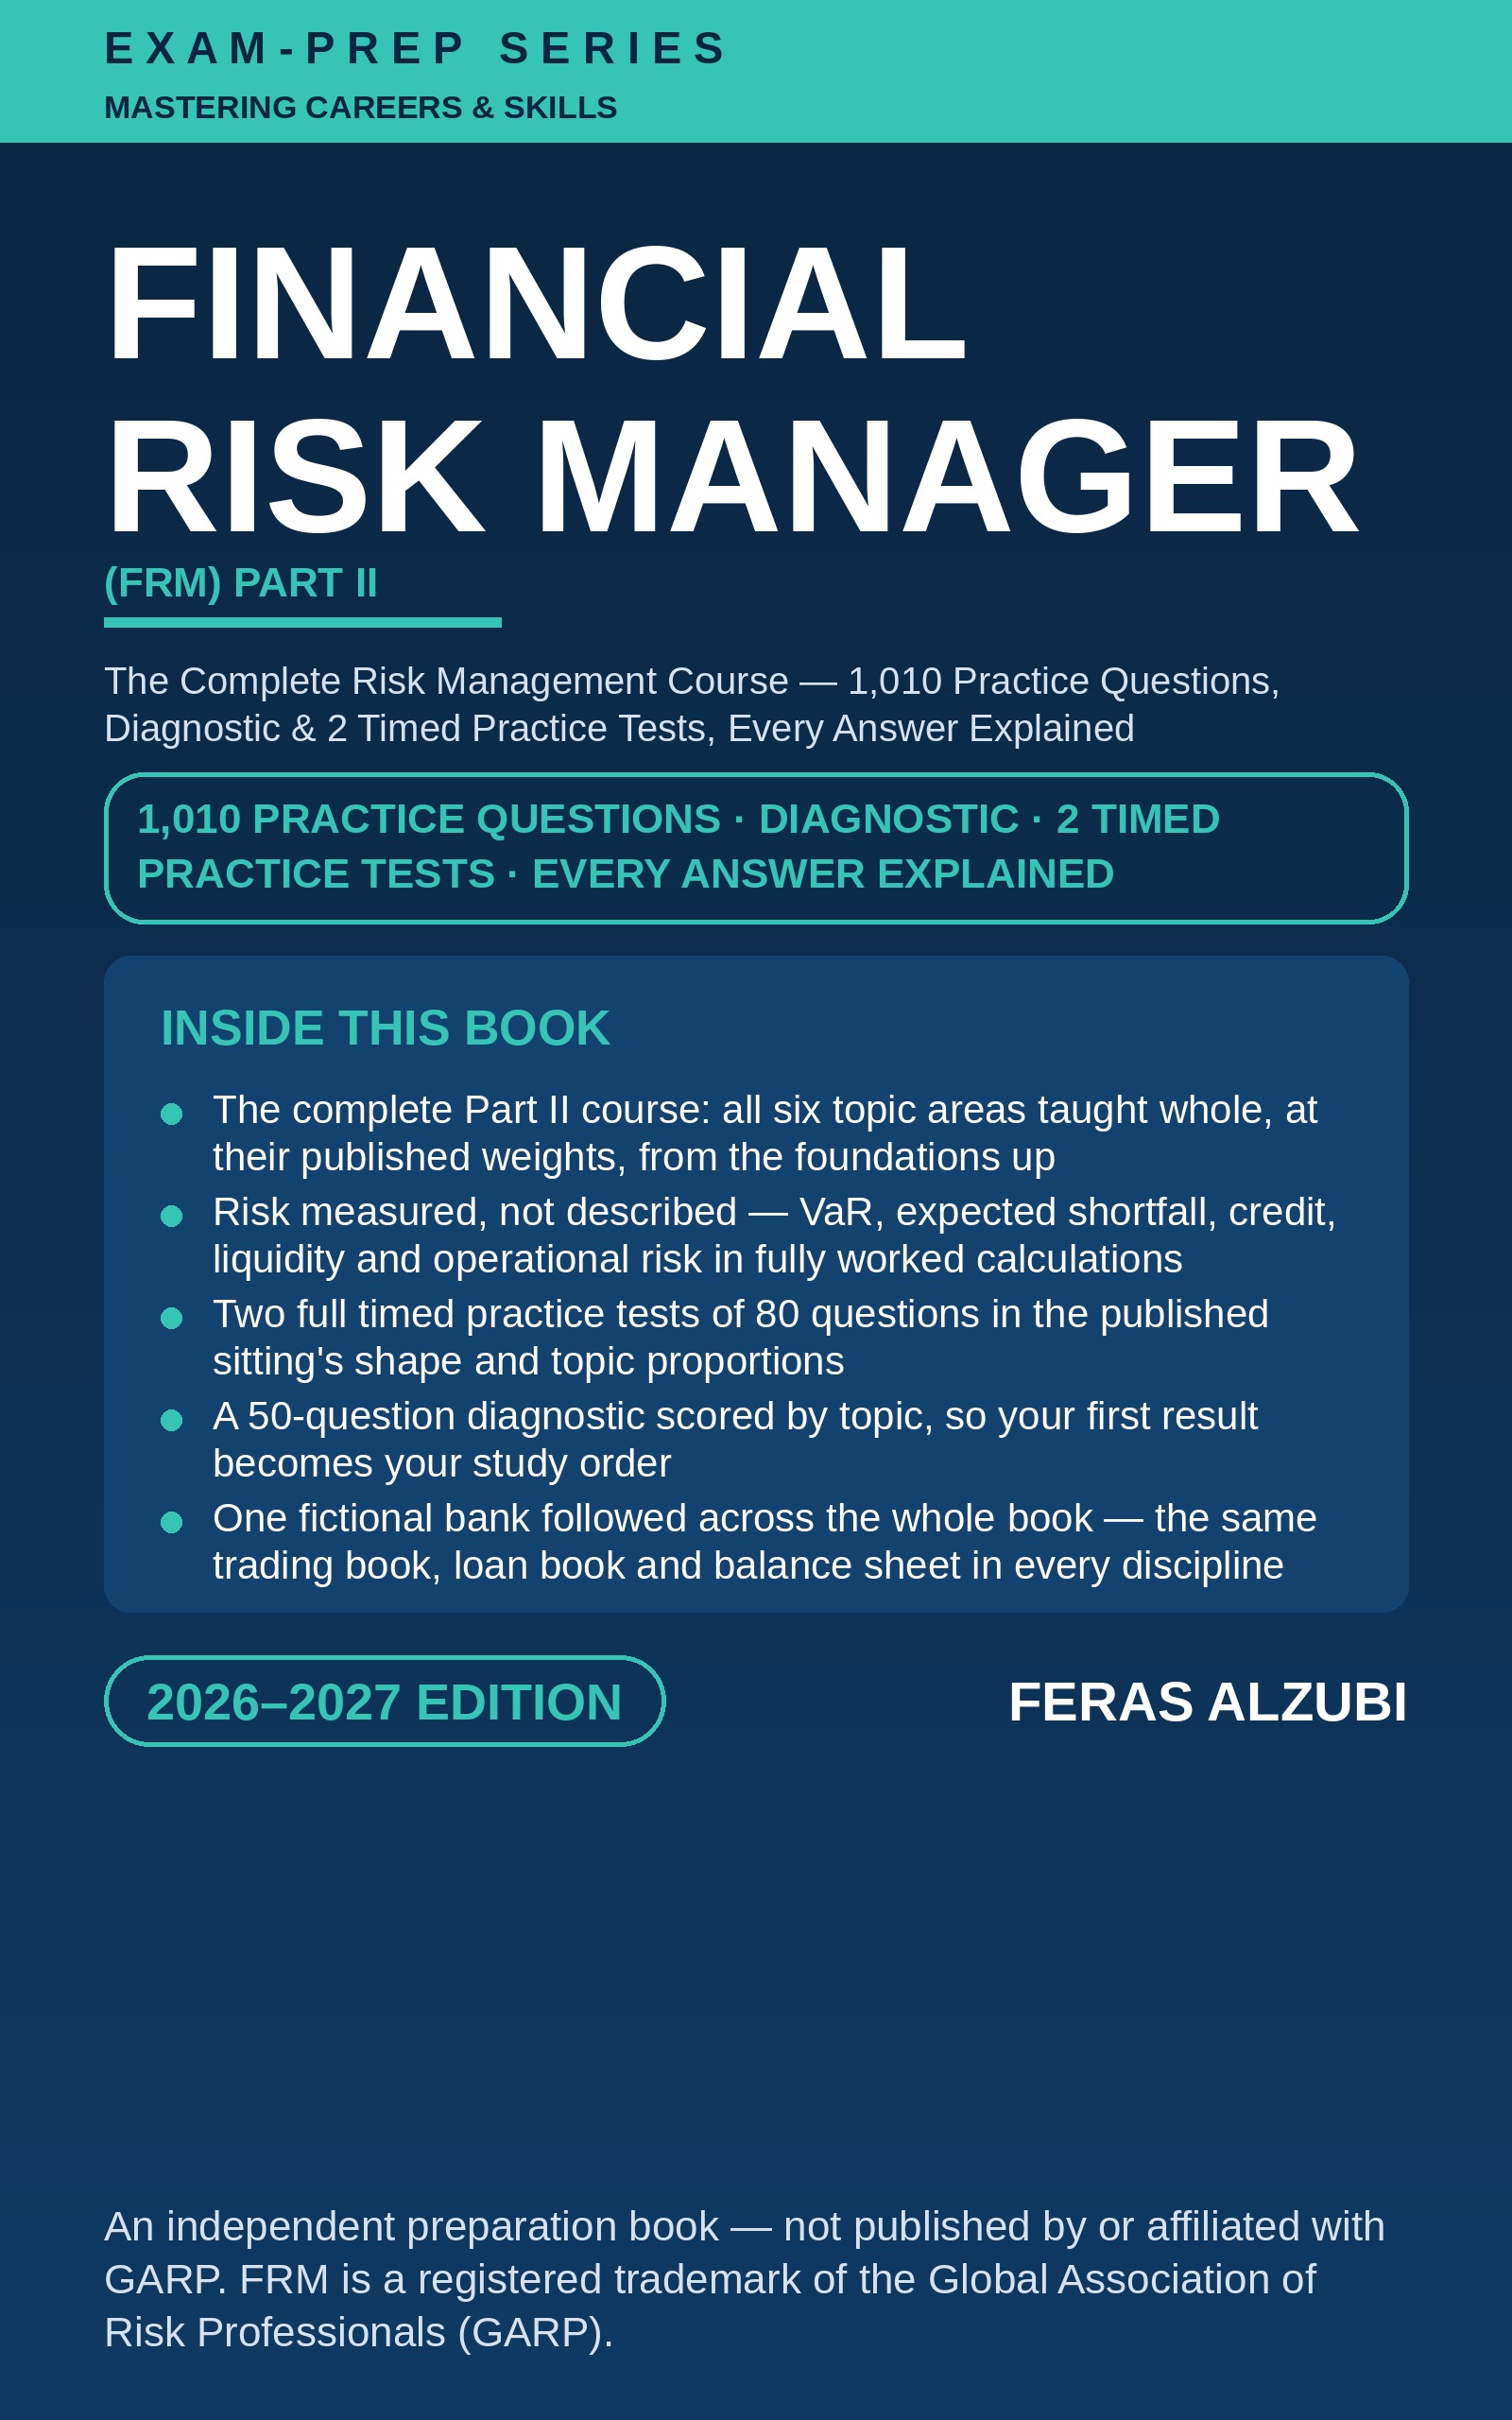
The Complete Risk Management Course — 1,010 Practice Questions, Diagnostic & 2 Timed Practice Tests, Every Answer Explained
Payments are securely processed by Payhip.
Sample opens the free first chapter right here on this site — read it instantly, no download needed.
Preparing for the FRM Part II examination? This is the complete Part II course in one book — the whole body taught from its foundations, plus 1,010 practice questions with every wrong answer explained. The Financial Risk Manager (FRM) Part II examination, administered by the Global Association of Risk Professionals (GARP), is the second of the two examinations for the FRM designation: 80 multiple-choice questions in four hours, weighted 20% market risk, 20% credit risk, 20% operational risk and resilience, 15% liquidity and treasury risk, 15% risk management and investment management, and 10% current issues in financial markets. This book teaches that entire body in 40 chapters, in the examination's own proportions — and because Part II stands on Part I foundations, it teaches those first, from zero, inside the same cover: probability, distributions, simulation, bonds, derivatives, and portfolio basics, briefly and sufficiently, before the Part II work begins.
What this book teaches. Market risk — VaR estimated three ways and mapped to risk factors, backtesting with the Kupiec and Christoffersen tests and the Basel zones, expected shortfall and coherent risk measures, extreme value theory, copulas and dependence, term structure models, volatility smiles, and the FRTB market-risk framework. Credit risk — credit analysis and ratings, the Merton structural model, hazard rates and reduced-form pricing, expected and unexpected loss, credit VaR, counterparty exposure, CVA and the xVA family, credit default swaps priced leg by leg, and securitization waterfalls with losses allocated tranche by tranche. Operational risk and resilience — frameworks and governance, the loss distribution approach and the Basel standardized approach computed in full, model risk and validation, cyber risk and operational resilience, financial crime and third-party risk, bank stress testing, RAROC, economic capital, and the Basel Accords. Liquidity and treasury risk — the liquidity coverage and net stable funding ratios computed line by line, cash-flow modeling and liquidity stress testing, funding models and repo, the contingency funding plan, funds transfer pricing, cross-currency funding, and balance sheet management. Risk management and investment management — factor theory and portfolio construction, risk budgeting with marginal contributions, performance measurement and attribution, hedge funds and private markets, risk monitoring, due diligence, and asset liquidity. Current issues — the published 2026 themes taught as risk themes: artificial intelligence, private credit, geopolitical risk, rising government debt, cryptocurrency and digital assets, and digital resilience (GARP's own Current Issues readings are published online only; these chapters teach the themes as risk method and point you to GARP's current list). One fictional bank — Halloran Bank — is followed through the whole book, so the same trading book, loan book, and balance sheet are measured again and again as the disciplines change: risk here is measured, not described — every model is shown in a fully worked calculation before it is practiced.
Who it is for. FRM Part II candidates anywhere in the world — Part I passers (and same-administration candidates) who want the whole Part II body taught whole, to a real standard, with the examination's own form at the end of the road.
What's inside (every count verified against the actual book):
The honest boundaries, stated plainly. This book teaches Part II. Part I is a separate examination and is not this book's subject — the foundations chapters prepare you to follow Part II, they do not replace Part I study. Passing Part II alone confers no certification: the FRM designation requires passing Part I and Part II and submitting two years of professional work experience in a risk-related field, as GARP publishes. GARP reports results as pass or fail only and publishes no passing score, so this book prints none and promises no result — no book honestly can.
Read the first chapter free — the sample on this page is Chapter 1 of this book, exactly as it appears in the full edition.
From the Mastering Careers & Skills library — complete A-to-Z professional teaching books for careers, trades, and certifications.
An independent study guide. Not affiliated with, endorsed by, or approved by GARP. FRM is a trademark of the Global Association of Risk Professionals, used here only to identify the examination this book prepares you for.
Refunds: Please read the free sample chapter before you buy. This is a digital ebook, delivered instantly by download. If the file is defective, or you cannot open or download it and we cannot fix the problem, you will receive a full refund — email us within 14 days of purchase. Because the book is delivered instantly as a downloadable file, all other sales are final.